Your Ad Here for $0.03 per day!

Tuesday, August 29, 2006

Gold Investment - II

This is my second series on gold investment. In my first blog, I only managed to explore the gold investment opportunities offered by Maybank. This time, thanks to Nik2004 from another Real Estate Forum, I came to know the gold offering by UOB Bank, which is much better than of Maybank.

UOB Bank offers a number of physical gold tradings, such as Australian Nuggets, Gold Maple Leaf, KineBar, Pamp Gold and Singapore Lion. Similarly, they come in several sizes in ounce (oz) or gram (g). And of course, the most economic in term of buy/sell spread is again the largest size gold, which is 1 oz. I found that 1 oz Aust Nuggets, Gold Maple Leaf and Singapore Lion has the cheapest spread, which is about 2.24% base on bank selling price. Compare to Maybank Kijang Emas which is about 3.18%, UOB offerings definitely more attractive. I found an intriguing fact which is this buy/sell spread determined by bank with each type of gold investments are actually not fixed. As of today, the spread with the few types of gold from UOB is RM56-57, but in a few weeks back, it was actually at RM65-66. Same case to Maybank, very puzzling! Nevertheless, with the quite big of gap between UOB and Maybank gold, I believe that UOB ones will still be a better buy at anytime. For UOB daily gold price, please refer to this link.

Again, I made a call to UOB bank to confirm that these golds are not actually available at their every branches. Only selected branch will sell certain types of gold but most of them will able to buy back all types of gold in their offering. So, in order to make sure your gold trading can be done at specific branch, make sure you call them to check out before make your visit. All UOB branches and their contact numbers can be found here.

To store your gold, it is also best kept in a safe deposit box in a bank, by paying a small annual fee. Unfortunately, I checked through UOB website and safe deposit box is not one of their service / product offered. It is a pity that one has to carry out the gold from UOB and keep it with other banks that offers such service. Of course, it will not be a problem if one has a safety box at home...hahaa. This is the part of gold investment that I hate most.

I have decided to allocated about 20% of my total investment value in gold. And after much consideration, I will buy the 1 oz Gold Maple Leaf because of its reputation and cheaper cost. At current entry price of gold about USD610-630 per oz, I think it is a good bet with the hope that gold will bounce back later this year and thus hedges partial of my money from inflation.

What do you think about gold? Please feel free to leave your comment.


This blog is best viewed with Firefox browser. Download link at side bar.

Labels:

Saturday, August 05, 2006

Starhill REIT


With my recent interest in REIT, I decided to take a deeper look into another seem "promising" REIT, Starhill which is among the few available in the market now.

Starhill REIT is currently owned 51% by YTL corp while only 49% is from public. Assets of Starhill REIT are Lot 10, Starhill Gallery and JW Marriott Hotel, which are all strategically located within the golden triangle of Klang Valley. Both Lot 10 and Starhill Gallery are currently enjoying near full occupancy rate, with majority of leases expiring by 2008.

Starthill REIT has indicated that they will distribute near 100% of income as dividen for the period to 1H FY2007, and thereafter 90% for each financial year. For the latest income distribution announced during end of last month (1H FY2006), which is 3.4524 sen per unit, it representing approximately 100% as what they have claimed. If Starhill can maintain the same income for the full FY2006, this will translate to ~7.5% yield, which is attractive.

However, if one delved into more details of Starhill, one will observe its future potential is limited. Firstly, the management of Starhill REIT (which is Pintar project Sdn Bhd, 70% subsidiary of YTL Land) has no plan to aggressively acquire new property (besides those owned by YTL) into its portfolio to improve its yield.

Secondly, the rental hikes of all current 3 properties of Starhill are very limited. JW Marriot Hotel only provides ~1% rental hike annually; Autodome, which is a subsidiary of YTL contributes ~67% rental income for Starhill Gallery, thus there is a conflict of interest for any rental hike; and Lot 10 is unlikely to fetch any significant increase in rental due to stiff competition nearby, e.g. Berjaya Time Square etc.

Thirdly, the distribution rate after 1H FY2007 will be reduced to 90%, effectively lower its overall yield.

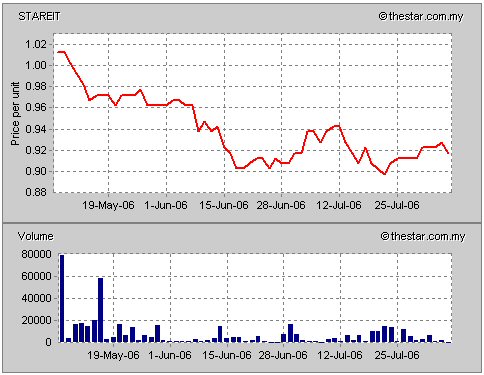
With all the above factors and unfavorable interest rate outlook for REIT in the past 6-9 months, its share price has dropped from its peak of RM1.07 to now RM0.915, which is below its IPO price of 0.980. NAV per unit as of 4-Aug-06 is quoted at RM0.983, about 6.9% lower than its current share price.

I personally think that the annual yield for Starhill will remain at ~7% until 1H 2007 base on its current share price of RM0.915. After that, I believe that its yield will drop to 6% or below due to reduced distribution rate and bleak outlook for shopping mall related properties when economy takes a downturn. It will be worse when the bulk of Lot 10 and Starhill Gallery leases expired by 2008, if recession happened at the same time.

As such, taking into account also the risk of depreciating share price, I personally will only consider to buy Starhill REIT for short term (1 year or less) if its share price hits 86 sen or less. This will fetch a yield of ~8%, and at the same time, minimizing the downside risk for capital preservation.


This blog is best viewed with Firefox browser. Download link at side bar.

Labels: ,

Wednesday, August 02, 2006

Axis REIT


I bought Axis REIT 2 months ago after reading the cover story from Personal Money magazine and a book "Road to Riches with REITs" by the famous sifu in capital market, Sherilyn Foong. At that time, I got different recommendations from the 2 sources, book and magazine.

Sherilyn recommended REIT investment strongly. As from her point of view, REIT is sort of "optimized" version of property investment, the next big thing in Malaysia (which was true for some times, but the heat faded off quickly, and the book was written in 2005). While on the other side, concerns of hiking interest rate (which renders the yield of REIT less attractive compare to fixed deposit), less than perfect regulation such as high taxation (28%) for foreign investor, too many red tapes for buying and selling property...etc from the magazine discouraged readers to invest in REIT.

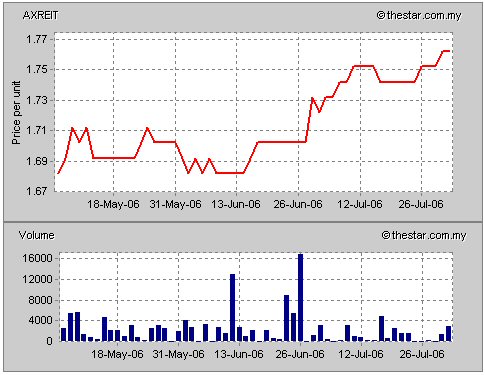
Nevertheless, because of my target is to invest into some stable, relatively high yield generating stocks, I've decided to bet a small amount in REIT. Naturally, for one to invest in REIT of Bursa, there is only limited options, which are UOA, Tower, Starhill and Axis REIT. Despite Axis REIT price has appreciated quite a lot from its IPO of RM1.25 (while others are about or even below their IPO), I have decided to invest in Axis, because of the main reasons as below:

a) Most actively managed, constantly acquires new property for yield improvement

b) Commited dividen payout rate of 95%

c) Strategic properties with high tenancy rate, ~99% and long term MNC occupants such as AIA, Tenaga, Fuji Photo, Fuji Xerox..etc

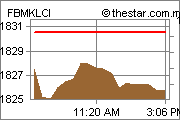
Its share price has remained very stable along these 2 months, despite KLCI has fluctuated in range 885 - 935 points. And yesterday, Axis REIT brought another good news to its investor. With 6.2 sen interim dividen, which is equal to 97.2% dividen payout rate, it is impressive to me.

"Axis Real Estate Investment Trust (Axis REIT) posted a net profit of RM14.79 million for the second quarter ended June 30, 2006.....
Revenue for the quarter ended June 30, 2006 was RM9.64 million while basic earnings per share was 7.18 sen. Axis REIT manager Axis REIT Managers Bhd also declared a 6.2 sen tax exempt interim dividend....."

Quoted from The Edge Daily, 01-Aug-06

If Axis can maintain this earning for 2nd half of the year, it will translate to ~12 sen per year. For the share price of RM1.68 (which I've purchased), this is equal to ~7.1% yield. At this rate, and judging from the stability of its share price (almost non-correlation to KLCI), I have to say that Axis REIT is a very attractive vehicle for me to temporarily place my spare money. Even if I quit before the next dividen payout, I will already received 6.2 sen (i.e. ~3.7%, which is almost equal to 1 year return of fixed deposit in bank). My calculation has also excluded the potential of capital appreciation, in my case, it has already rised ~4.7%.

In addition, I think the overall economy condition now is favouring toward investment of REIT, because:

a) Interest rate hike seem to put on a pause, with economy slowing down globally and locally, easing the concern of inflation

b) Relaxation of regulation / guideline from SC for growth of REIT. Latest change as reported in The Edge Daily as link

c) Potential lower taxation for foriegn investor by government in coming budget. This will attract foreign investment and price appreciation for current REIT.

So, for those who are interested to jump into the boat of REIT investment, make sure you grab some well managed REIT like Axis. The execution date of its current dividen payout is on 17-Aug. For me, I will collect more Axis when its price resides after dividen payout, but before budget. Also, please note that income from REIT dividen is subjected to Malaysian income tax base on individual bracket.

Related links:
http://biz.thestar.com.my/news/

This blog is best viewed with Firefox browser. Download link at side bar.

Labels: ,

Sunday, July 23, 2006

Gold Investment

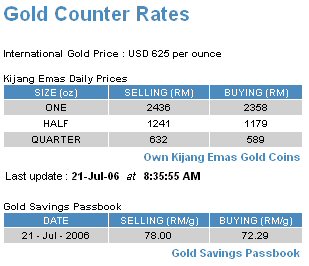
Maybank offers 2 types of gold investment. They are Kijang Emas Gold Coins and Gold Savings Passbook. As can be seen from the daily price quoted beside, the margins between buying and selling price are very different for each type of investments, and sizes (oz). For Kijang Emas Gold Coins, the margins for 1oz, 0.5oz and 0.25oz are 3.31%, 5.26% and 7.30% respectively. For Gold Savings Passbook, its margin is even higher, at a costly 7.90%! I guess this is because Gold Savings allow the smallest trade size (5g), thus it comes with a hefty buying/selling price difference.

Obviously, the most "economic" choice to invest in Gold is to buy the 1oz Kijang Emas Gold Coins. However, there are few drawbacks which I personally do not like. First, the gold coins is only sold at specific branches, which means inconvinient to trade. Secondly, they are physically gold coin, you have to carry them around during buying or selling, and even have to find a place to save keep them. Gold Savings Passbook is a more convinient way, but the 7.90% margin is hard to swallow. Unless you can forsee that the future gold price will rise >12%, otherwise it is not any better than FD.

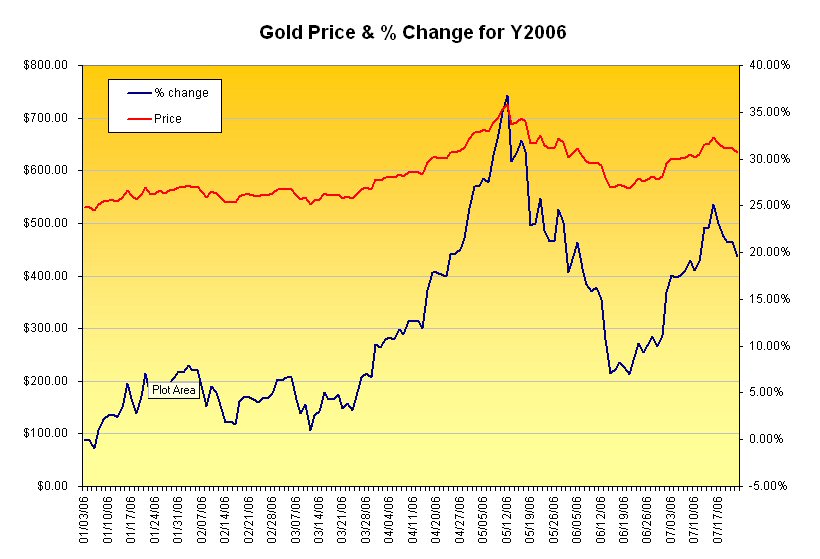
I made a chart as below of the price movement of Gold for Y2006 (until 21-July-2006), quoted from www.usagold.com. Hope this gives some hints.....


This blog is best viewed with Firefox browser. Download link at side bar.

Labels:

Fixed Deposit Rate of Malaysia Commercial Banks

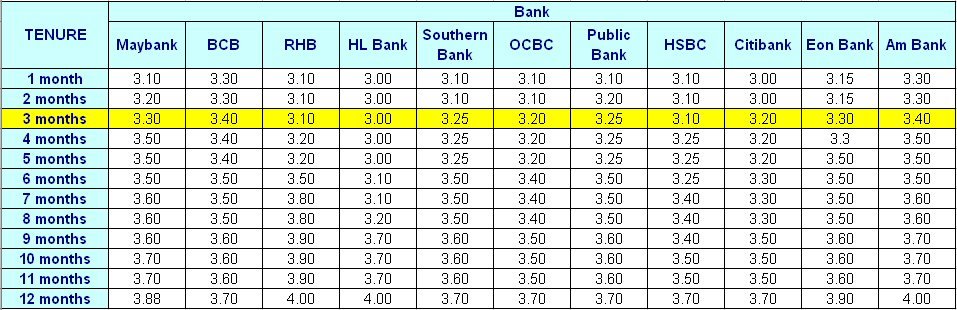
I am searching the best interest rate offered by various M'sia commercial banks to park my money temporarily and this is what I've found. I'm only interested in 3-months fixed deposit and sadly, despite increased of BLR, I still find they all unattractive. The highest rate offered by BCB and AmBank is merely 3.40%. At this rate, the current inflation level is probably higher!

Look likes I have to find another better investment vehicle to place my money. Unit trust (bond fund) and Maybank Gold Savings are under my consideration. However, need to do some homeworks on both of these options before I can decide. Otherwise, can someone recommend me any "real" defensive stock that can still generate reasonable return (from dividen and capital preservation) during bad time? I really doubt there is any.....

P.S: If one does not mind the miserly low interest rate of FD, I find that AmBank is the best Bank which offers the highest rate regardless of tenure. A thumb up to AmBank for beating all other banks flatly!


This blog is best viewed with Firefox browser. Download link at side bar.

Labels: